WeBuyCars crashes from hero to zero

WeBuyCars’ share price plummeted by 54.3% over the last year, which means that the company’s market cap declined by R12.9 billion.
WeBuyCars is South Africa’s premier secondhand car dealer, moving approximately 15,500 vehicles through its operations per month.
The business model includes buying secondhand cars, making slight improvements when needed, and then selling them through auctions and its supermarkets.
The company focuses on passenger and commercial vehicles, motorcycles, trailers, caravans, and, in some areas, boats.
WeBuyCars, founded in 2001 by brothers Faan and Dirk van der Walt, showed exceptional growth in its first two decades.
It was so successful that Transaction Capital bought a 49.9% stake in the company for R1.84 billion in September 2020.
The next year, it increased its holding to 74.9%, gaining majority control. However, Transaction Capital fell on hard times, forcing it to sell this stake.
It unbundled WeBuyCars and listed it on the Main Board of the Johannesburg Stock Exchange (JSE) on Thursday, 11 April 2024.
As a newly listed entity, WeBuyCars continued its strong growth and cemented its position as the dominant player in South Africa’s secondhand car market.
In the first fifteen months after being listed on the JSE, WeBuyCars’ share price increased by 191%, from R20.50 per share to R59.75.
However, since then, the company has struggled to maintain this momentum. Over the last year, the share price declined by 54.3%.
This means the company’s market cap declined from R23.75 billion to R10.85 billion, a loss of R12.9 billion in a year.
WeBuyCars struggles with increased competition
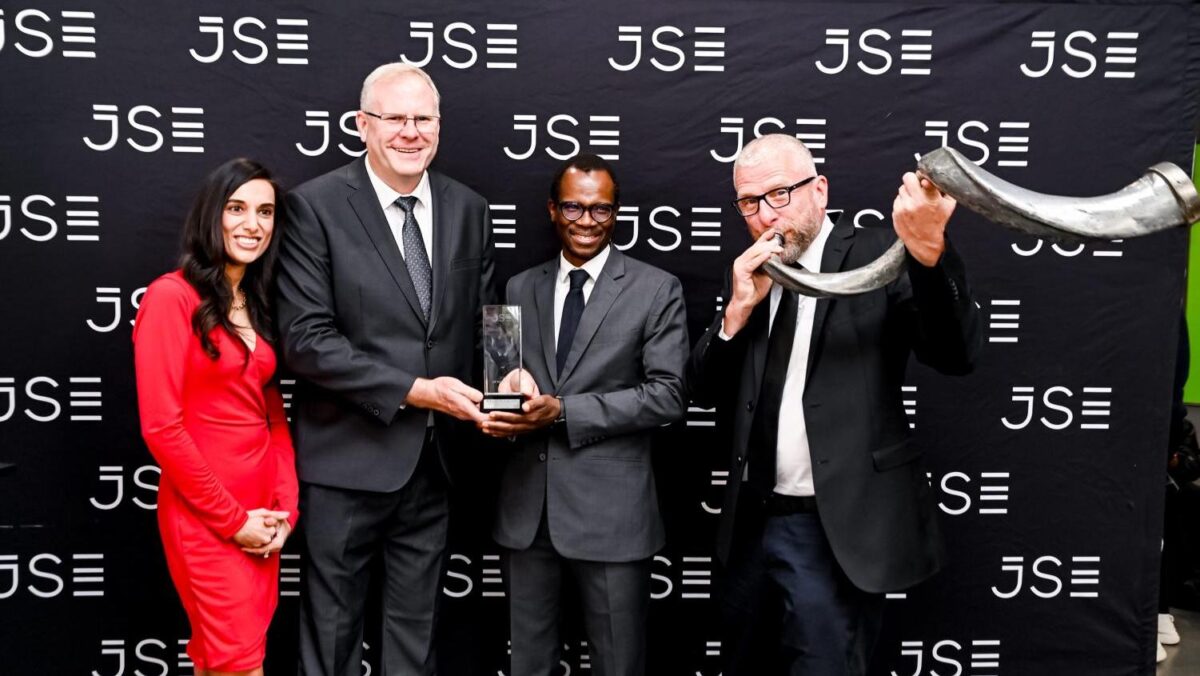
WeBuyCars built a dominant business, with 3,722 employees, 20 supermarkets with 15,614 parking bays, and 109 buying pods across South Africa.
However, it has faced challenges over the last two years due to increased competition and a tough economic environment.
WeBuyCars’ latest half-year results showed many positives, including revenue increasing 7.8% to R14.2 billion and buying and selling volumes rising marginally.
However, adjusted earnings before interest, taxes, depreciation, and amortisation (EBITDA) decreased 1.3% to R789.5 million.
Core headline earnings fell 1.6% to R500.1 million, with per-share value declining 1.7% to 119.7 cents.
FNB highlighted that this indicated mixed performance, with solid top-line momentum while the bottom line slowed.
It added that WeBuyCars faces many challenges, including exposure to economic downturns and the interest-rate environment.
“Periods of severe economic distress could have an adverse impact on demand and sales of secondhand cars,” it said.
The recent South African Reserve Bank interest rate increase and the record fuel price increases are examples of things which hurt the company.
Another problem is that consumers have grown increasingly wary about the condition and quality of vehicles being sold by WeBuyCars.
“There have been numerous complaints about mechanical and electrical issues arising after sales have been completed,” FNB said.
There are also concerns about the company’s after-sales service, with a considerable number of consumers left unsatisfied after purchasing their vehicles.
However, the biggest threat is affordable new Chinese vehicles, which have moved consumers away from the secondhand market,
This put pressure on WeBuyCars’ margins, and there are no signs that the situation will change anytime soon.
There are still positive things about WeBuyCars

Despite the significant challenges, there are many reasons for investors to be optimistic about WeBuyCars’ prospects.
One is that the used-vehicle market in South Africa is much more defensive than the new-vehicle segment.
Another is that used-vehicle dealers are agnostic to imports and currency volatility, eliminating a cyclical component relative to local-listed peers.
WeBuyCars also has many advantages over its competitors, including its digital real estate, proprietary technology, and insights from collected data.
Another advantage is its substantial brand recognition in a market segment that has historically been marred by a consumer trust deficit.
These advantages were enough for Mark Du Toit from Oyster Catcher Investments to select it as his stock pick.
“The share price has had a tough time this year, falling to R25 a share amid concerns that the business model might be broken,” he told Business Day TV.
“However, we don’t think the business model is broken at all. There has been a reduction in second-hand car prices as new Chinese vehicles enter South Africa.”
He highlighted that WeBuyCars’ average selling price per vehicle is R148,000, and they make a margin on every unit they sell.
“The reduction in inventory values is now mostly complete and largely priced in. Furthermore, having finished their major capacity rollout,” Du Toit said.
This will allow WeBuyCars to focus on filling the bays and increasing sales turnover, which should boost profitability.
“Post this reporting period, we expect their earnings to look significantly better and return to growth, none of which is currently reflected in the share price,” he said.
 Loading ...
I purchased a Hyundai from Brackengate branch which was misleadingly advertised on the windscreen as a Hyundai Grandi10 1.25 which is top of the range and fraudulently invoiced as such. It turned out to be a Hyundai Grandi10 1.0l which is bottom of the range worth at the time R38,000.00 less than the car I thought I had bought. It turned out to be a rebuilt write off with the registration documents kept as used instead of Code 3. I have the proof that it was written off by Auto and General in 2020 and I purchased it in 2024.I paid R127,000.00 for this piece of scrap. The Dekra report was completely false as it did not mention that the chassis was bent, the strut was bent,it was full of welding underneath and the engine was welded to the chassis because there was no room for am engine mounting. I have the Dekra report which also states that the interior was General wear and tear meanwhile the door panels were smashed and the cubbyhole was pushed under the dashboard. I also do not think that this was the vehicle that I viewed because at the time I was in and out of hospital so the valet company Auto Armor fetched it the following morning for me. After finding out all of this 3 and a half months later ( the Consumer Protection Act is 6 months) I emailed Monica Birkenbach in thier legal department who said simply sorry it’s too late which it wasn’t and that even though it wasn’t the 1.25 Fluid that was advertised I still got it under thier asking price. I tried the Ombudsman twice and got nowhere and sent the Competition Commission 3 emails with all the proof of what I found ( 11 pages) and never even received a reply. I then had a zoom meeting with Monica Birkenbach and Stefan Le who knows about it and they both went completely against the CPAct so they are both ignorant of the act or both dishonest. There is no other reason. In the end these two offered to take it back for R50.000. I have since replied to one of thier adverts and informed the company that it is a rebuilt write off but the papers say used and I was again offered R50.000. I received that offer on paper and the agent phoned me so they can’t say they don’t buy scrap. This WBC company is an absolute disgrace to the motor industry and as far as I am concerned a bunch of crooks. I have been to a lawyer now and it has taken 2 years to finally get the summons delivered. When it goes to court I am going to invite all the newspapers and news outlets to come and see how this company operates. My advise to the public is don’t go near them. The Competition Commission recently fined them R2.5 million for their total disregard of the CPA and ordered them to pay for complainant repairs totalling either R5.4 million or R54 million. So they are known for this. I also emailed Monique from Customer Care and she replied asking for the car details and said she would come back via email within 10 days and twice we emailed asking for the outcome and she never replied. So this is how they operate. I hope the two brothers Faan and Dirk read this as I have told this story at every opportunity and on Facebook and will continue to do so because everything is true. These two individuals must have cost thier company millions.